---
title: Insurance Gap Care When You’re Between Plans
description: Insurance gap care can help manage prescriptions, appointments, bills, and coverage options when a job change or life event leaves you uninsured today.
image: https://afocirmbqdxnkyescnev.supabase.co/storage/v1/object/public/featured-images/7524cf5d-b4b1-4b41-9eb8-c8748cefd60d/workflows/f499f5b1-0e8c-41c5-aee8-d267da5b3b30.webp
---
- [For Employers](https://ful-health.com/for-employers)
- [Overview](https://ful-health.com/for-employers)
- [Business Case](https://ful-health.com/be/the-business-case)
- [What FUL Includes](https://ful-health.com/be/consider-ful)
- [Resources](https://ful-health.com/resource-center)
- [About Us](https://ful-health.com/about-us)
- Blog
- [Workforce Insights](https://ful-health.com/blog/workforce-insights)
- [Healthcare Guides](https://ful-health.com/blog/healthcare-guides)
- [Employer Resources](https://ful-health.com/resource-center)
[Get FUL →](https://ful-health.com/?get-ful=paid)
- [For Employers](https://ful-health.com/for-employers)
- [Overview](https://ful-health.com/for-employers)
- [Business Case](https://ful-health.com/be/the-business-case)
- [What FUL Includes](https://ful-health.com/be/consider-ful)
- [Resources](https://ful-health.com/resource-center)
- [About Us](https://ful-health.com/about-us)
- Blog
- [Workforce Insights](https://ful-health.com/blog/workforce-insights)
- [Healthcare Guides](https://ful-health.com/blog/healthcare-guides)
- [Employer Resources](https://ful-health.com/resource-center)
[Get FUL →](https://ful-health.com/?get-ful=paid)
[](https://apps.apple.com/us/app/ful-cashpay-health-savings/id6742342974) [](https://play.google.com/store/apps/details?id=com.ful.cashpay)
## Get FUL on your phone
Scan with your phone's camera and we'll take you to the right app store.
Or download it directly
[](https://apps.apple.com/us/app/ful-cashpay-health-savings/id6742342974) [](https://play.google.com/store/apps/details?id=com.ful.cashpay)
# Insurance Gap Care When You’re Between Plans
[Carrie Tedore](https://ful-health.com/blog/healthcare-guides/author/carrie-tedore) · November 11, 2026
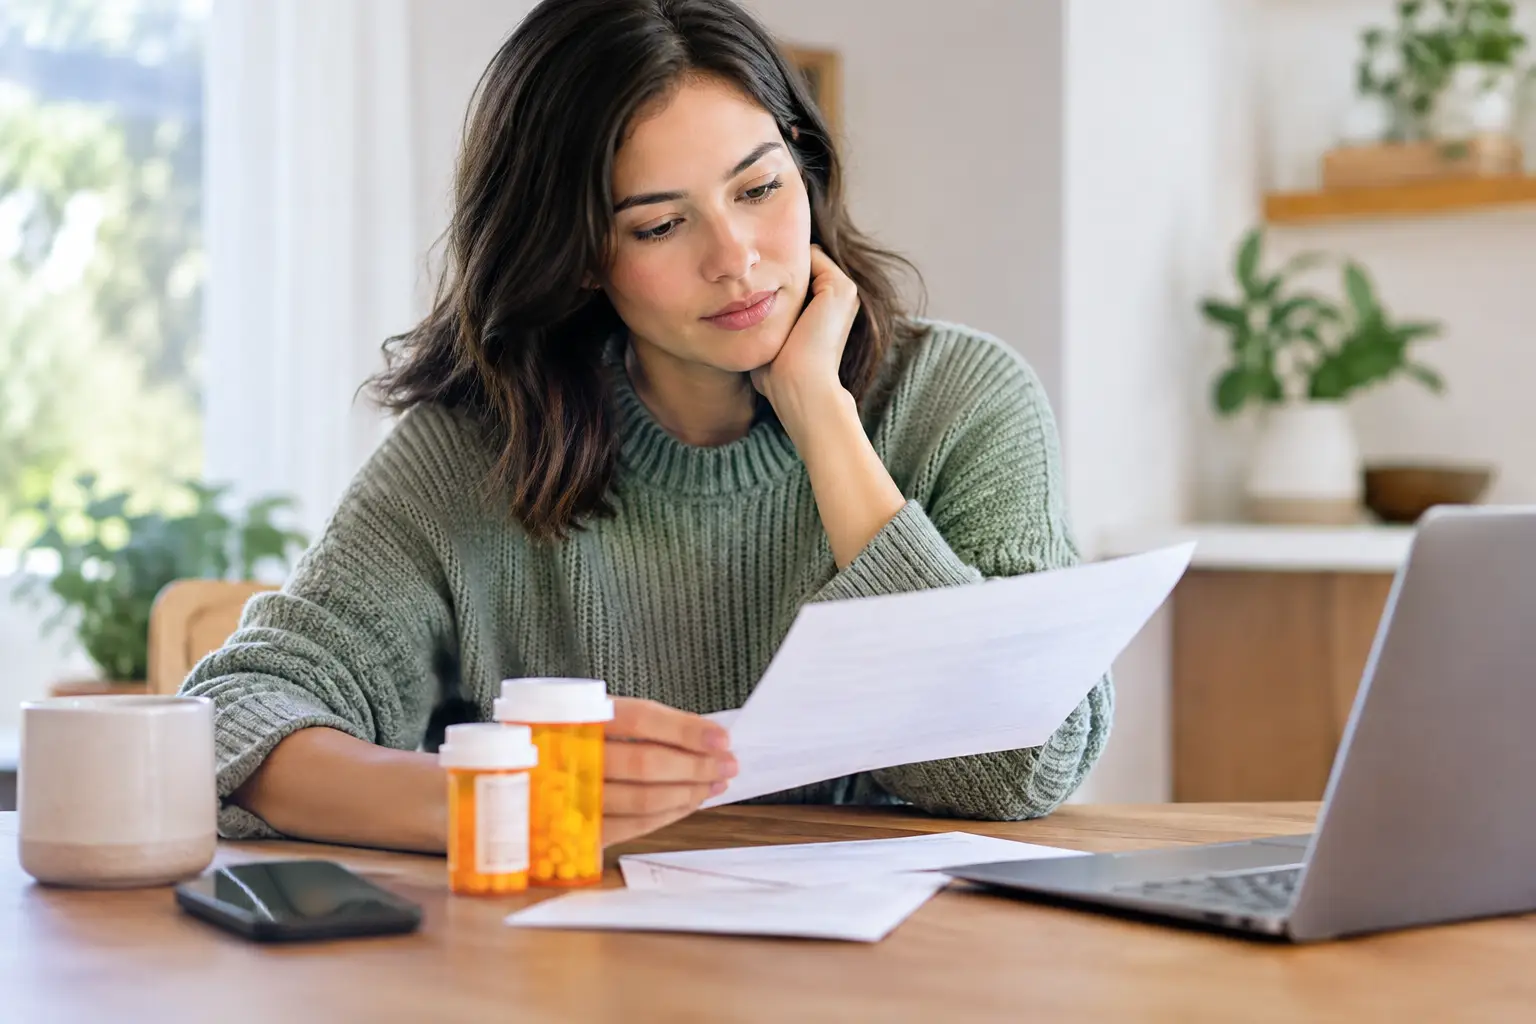
Your insurance ended, but your prescription refill is due next week. Or your child needs a follow-up appointment before new coverage begins. This is the moment insurance gap care matters: finding a safe, affordable way to handle the healthcare needs in front of you while you are between plans or facing costs your plan will not cover.
A gap in coverage does not mean you have to put every healthcare decision on hold. It does mean you may need to compare prices, protect access to medications, and check whether you qualify for new coverage sooner than you think. Start with the need that cannot wait, then make a plan for the rest.
## What insurance gap care means
Insurance gap care is practical healthcare support during a lapse in insurance coverage or when insurance is not making care affordable. It can apply after leaving a job, aging out of a parent’s plan, moving, losing Medicaid eligibility, waiting for employer coverage to start, or dealing with a high deductible that makes you feel effectively uninsured.
The goal is not to replace health insurance. It is to avoid unnecessary delays, surprise bills, and missed medications while you sort out coverage and costs.
Your options will depend on the care you need. A prescription refill, a routine lab test, a new symptom, an imaging order, and a hospital bill each call for a different next step. The most useful question is not, “How do I get healthcare without insurance?” It is, “What do I need to solve right now, and what is the lowest-risk way to do it?”
## Handle the need in front of you first
If you have a serious or life-threatening emergency, seek emergency care. Do not delay because you are uninsured or unsure what a visit may cost. For non-emergency needs, a little preparation can make care far more manageable.
### Keep prescriptions from becoming an emergency
If you take a medication regularly, check the refill date now rather than waiting until you have only a few pills left. Ask the pharmacy for the cash price and compare it with available [prescription savings](https://ful-health.com/blog/healthcare-guides/best-prescription-cash-discount-for-lower-costs). A medication can cost very differently at pharmacies a few miles apart, and the insurance price is not always the lowest price when you are paying out of pocket.
Your prescriber may also be able to discuss a lower-cost generic, a different dosage or supply size, or an alternative medication. Do not change or stop a prescribed medication on your own to stretch it. Tell the clinician or pharmacist plainly that cost is the problem. That gives them a real chance to help.
### Ask for the cash price before routine care
For many non-emergency services, including primary care visits, labs, imaging, and some urgent needs, you can ask for a self-pay or cash price before scheduling. Ask what is included and whether there could be separate charges for the facility, clinician, radiologist, or lab.
A lower advertised price is not always the lower final bill. For example, an imaging center may quote a reasonable scan price but exclude the radiologist’s interpretation. Get the estimate in writing when possible and ask whether a payment plan is available before the service.
If you already have an order for a lab test or imaging study, you may have more choices than you realize. The hospital location is not always the only place that can perform it. Comparing independent facilities and cash-pay options can be worthwhile, especially for planned care.
### Do not ignore a hospital bill
A hospital bill received during an insurance gap is not automatically final. Review it for errors, ask for an itemized bill, and find out whether the hospital has [financial assistance or charity care](https://ful-health.com/blog/healthcare-guides/hospital-financial-assistance-guide). Many nonprofit hospitals have programs for eligible patients, and some assistance may be available even if you have some income or partial coverage.
Apply as soon as you can, keep copies of documents you submit, and ask whether the account can be placed on hold while your application is reviewed. If the bill is already in collections, you can still ask the hospital whether financial assistance remains available.
## Check whether the gap can be shortened
Losing health coverage can trigger a Special Enrollment Period, which may let you enroll in a Marketplace plan outside the usual annual enrollment window. Deadlines matter, often running for a limited period before or after the loss of coverage, so check promptly rather than assuming you must wait until next year.
If you recently lost job-based insurance, COBRA may allow you to continue the same plan for a time. Its biggest advantage is continuity: you may be able to keep the same doctors and avoid restarting deductibles in certain situations. Its biggest drawback is cost, because you may have to pay the full premium yourself. Compare the monthly premium, deductible, provider access, and prescription coverage against Marketplace options before choosing.
Medicaid and the Children’s Health Insurance Program, or CHIP, are also worth checking. Eligibility varies by state and household circumstances, and people sometimes assume they earn too much or do not realize their children may qualify even when the adults do not. Pregnancy, disability, age, household size, and recent income changes can affect the answer.
A new employer plan may have a waiting period. Ask the benefits team for the exact effective date, whether coverage can begin on the first day of a month, and what documentation is needed. Knowing the date helps you decide whether short-term cash-pay care is enough or whether a coverage option is worth pursuing.
## Build an insurance gap care plan for your household
When coverage changes, make a short list of each household member’s active healthcare needs. Include medications, scheduled appointments, referrals, ongoing treatment, needed labs, and medical bills that still need attention. This is not busywork. It helps you avoid spending energy on vague worry while a refill, deadline, or appointment quietly becomes urgent.
Then separate needs into three categories: care that cannot wait, care needed in the next month or two, and care that can reasonably wait until coverage is active. For the first category, focus on safe access and clear prices. For the second, compare [cash-pay options](https://ful-health.com/blog/healthcare-guides/cash-pay-healthcare-when-it-can-cost-less) and coverage timelines. For the third, ask whether postponing is medically appropriate rather than deciding based on cost alone.
Keep records from your old plan, including the coverage end date, recent explanations of benefits, prescription information, and medical orders. These can help with enrollment, refills, billing questions, and continuity of care. If you change plans, confirm that the new plan is active before assuming a provider or pharmacy can bill it.
## Be careful with quick-fix coverage offers
When people lose coverage, they often see ads for plans that sound inexpensive and immediate. Some limited-benefit products do not cover the same services or financial risks as comprehensive major medical insurance. They may have exclusions for preexisting conditions, caps on payments, restricted benefits, or limited provider networks.
That does not make every alternative product useless. It does mean you should read what it actually pays for, what it excludes, and whether it is intended to bridge a short period or provide meaningful protection from major medical costs. Do not rely on a plan name, a low monthly price, or a sales promise alone.
## Get support that fits the problem
You do not have to solve an insurance gap in one sitting. Start with the deadline closest to you: a refill, a coverage-loss date, an appointment, or a bill. Then take the next practical step.
FUL can be useful when the problem is bigger than one appointment. The free app includes prescription savings and practical healthcare field guides, while eligible household members can use membership support for needs such as finding affordable labs or imaging, understanding hospital bills, and exploring Medicare, Medicaid, or CHIP eligibility. Membership is $16.99 per month for the household and includes unlimited $0 doctor visits, available 24/7, when physician access is the right need.
Being between insurance plans is frustrating, but it does not erase your choices. A clear price, a timely refill, a financial-assistance application, or the right enrollment path can turn a coverage gap into a manageable next step.
Ready to talk?
[Schedule a Conversation →](https://landing.ful-health.com/schedule-a-conversation)
[Contact](https://ful-health.com/contact-us)
©2026 ful.Health LLC All rights reserved.
[Privacy Policy](https://ful-health.com/legal/privacy-policy) [Terms of Service](https://ful-health.com/legal/terms-of-service)
```json
{
"@context" : "https://schema.org",
"@type" : "BlogPosting",
"author" : {
"@type" : "Person",
"name" : "Carrie Tedore",
"url" : "https://ful-health.com/blog/healthcare-guides/author/carrie-tedore"
},
"datePublished" : "2026-11-11T03:41:48.000Z",
"headline" : "Insurance Gap Care When You’re Between Plans",
"image" : [ "https://afocirmbqdxnkyescnev.supabase.co/storage/v1/object/public/featured-images/7524cf5d-b4b1-4b41-9eb8-c8748cefd60d/workflows/f499f5b1-0e8c-41c5-aee8-d267da5b3b30.webp" ],
"mainEntityOfPage" : {
"@id" : "https://ful-health.com/blog/healthcare-guides/insurance-gap-care-between-plans",
"@type" : "WebPage"
},
"publisher" : {
"@type" : "Organization",
"logo" : {
"@type" : "ImageObject",
"url" : "https://ful-health.com/hubfs/ful%20logo_full%20color_RGB.png"
},
"name" : "ful.Health LLC"
}
}
```